China Top 10 Full Screen Glass Suppliers in 2026?
China’s Full Screen Glass industry is expanding with sharper edges, thinner bezels, and stricter optical requirements. This guide examines ten notable Chinese suppliers for 2026.
The selection considers manufacturing experience, product consistency, customization ability, and communication reliability. It also reviews cover glass for smartphones, tablets, automotive displays, and industrial touch panels. Key checkpoints include glass clarity, edge strength, surface hardness, oleophobic coating, dimensional tolerance, and compatibility with curved or 2.5D designs. Small details matter. A clean cutout can reduce assembly delays.
Supplier evaluation should not rely on factory size alone. Production capacity, inspection systems, sample accuracy, and after-sales support deserve equal attention. Reliable manufacturers should explain their tempering process, coating performance, packaging method, and quality-control records. Buyers may also request test samples before approving large orders. This practical step often reveals more than a polished product brochure.
The ranking is intended as a research starting point, not an official industry verdict. Market conditions, equipment upgrades, export experience, and customer feedback can change during 2026. Some suppliers may perform strongly in mass production but offer limited support for smaller projects. Others may provide excellent engineering assistance while carrying higher costs. That trade-off deserves honest attention.
This article compares the strengths, limitations, and likely applications of each company. It avoids exaggerated promises and highlights questions buyers should ask. The best supplier is not always the largest. It is the one that delivers stable quality, clear documentation, and dependable cooperation. Yet no shortlist can replace factory audits, sample testing, and careful contract review.
Full-Screen Glass Scope: 0.33–0.55 mm Cover Glass and 2026 Demand
China’s top ten full-screen glass suppliers in 2026 should be assessed through measurable manufacturing evidence, not online rankings. The practical scope centers on 0.33–0.55 mm cover glass for narrow-bezel phones, tablets, wearables, and compact displays. This range demands careful control of flatness, edge strength, optical clarity, and touch sensitivity.
Demand is rising as device makers reduce bezels without sacrificing durability. The 0.33 mm option saves weight and space, but it leaves less tolerance for impact damage. Thicker 0.55 mm glass offers better stiffness, although it can increase stack height and device weight. That trade-off is easy to underestimate.
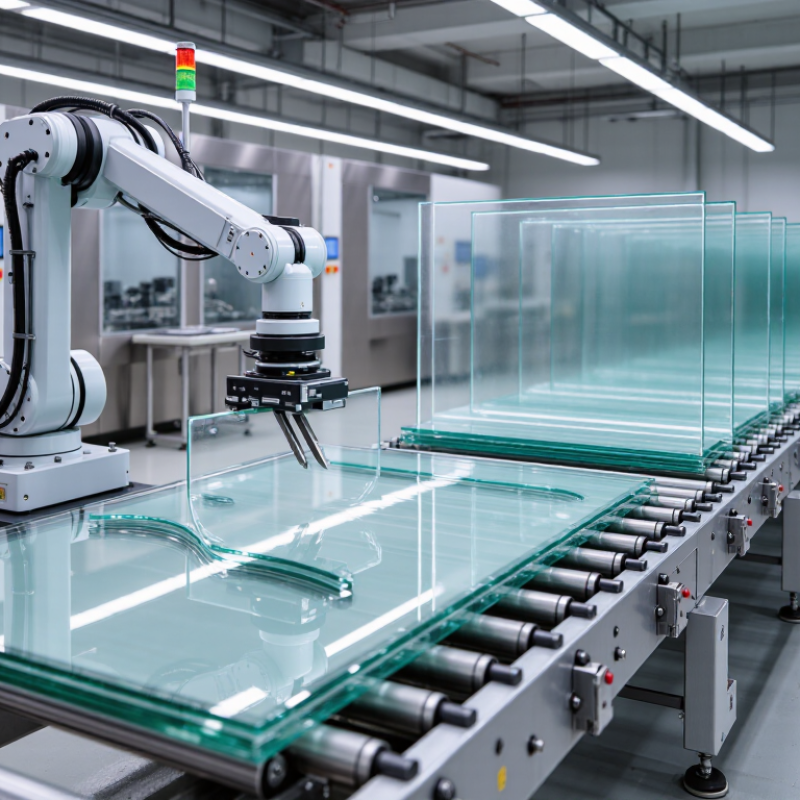
Supplier audits should examine CNC cutting, chemical strengthening, coating uniformity, and clean-room handling. Ask for lot-level inspection records, not only polished samples. Useful evidence includes haze readings, thickness variation, transmittance, surface hardness, and edge-chipping data. Reliability testing should cover drop impact, abrasion, thermal cycling, humidity, and repeated touch use.
A strong supplier can explain process limits clearly. Better still, its engineers can adjust tooling after pilot feedback. In my experience, early samples often look excellent under showroom lighting. Production lots may reveal coating marks, uneven black borders, or small edge defects. That gap deserves honest review. 2026 purchasing teams may also need shorter lead times, stable capacity, recyclable packaging, and traceable quality records. Forecasts remain uncertain, especially when screen sizes and device designs change quickly.
Supplier Comparison: 2D, 2.5D, 3D, OLED, and UTG Manufacturing Capabilities
China’s top ten full-screen glass suppliers in 2026 should be compared by process depth, not advertised scale. This shortlist examines 2D, 2.5D, 3D, OLED-cover, and ultra-thin glass (UTG) capabilities. Factory audits should verify bending radius, thickness tolerance, yield, and monthly output. A polished sample proves little.
Omdia’s Smartphone Display Market Tracker indicates OLED represents over half of smartphone panel shipments in several recent quarters. This increases demand for tighter flatness and ink-edge control. DSCC’s Foldable and Rollable Display Technology and Market Outlook continues to forecast double-digit foldable-panel growth. However, forecasts differ by shipment definition. That disagreement matters.
2D lines remain economical for rigid OLED and LCD designs, with simpler tooling and faster changeovers. 2.5D adds edge curvature and requires better CNC control, chemical strengthening, and inspection. 3D glass needs matched forming, mold compensation, and optical distortion control. UTG is a different test. Thinness alone is insufficient. Suppliers should provide bending-cycle data, crease behavior, particle control, and lamination compatibility. OLED-ready factories should report haze, transmittance, surface hardness, and dimensional capability, ideally using ISO 2859 sampling and statistical process control. For a credible 2026 ranking, I would separate verified capacity from management estimates and request recent lot data before scoring ten suppliers. The largest furnace may not indicate the strongest partner. Failure analysis often reveals more.
China Top 10 Full Screen Glass Suppliers in 2026
Supplier Comparison: 2D, 2.5D, 3D, OLED, and UTG Manufacturing Capabilities
| Rank |
Anonymized Supplier Profile |
Primary Manufacturing Focus |
Typical Glass Materials |
2D Glass |
2.5D Glass |
3D Hot-Bent Glass |
OLED Cover Glass |
UTG Capability |
Production Scale |
Typical Application Coverage |
| 01 |
Supplier Profile 01 |
Integrated cover-glass manufacturing |
Aluminosilicate, chemically strengthened glass |
Commercial |
Commercial |
Commercial |
Commercial |
Selective |
Large-scale |
Smartphones, tablets, automotive displays |
| 02 |
Supplier Profile 02 |
High-volume 2D and 2.5D cover glass |
Aluminosilicate, soda-lime for non-premium uses |
Commercial |
Commercial |
Selective |
Selective |
Not listed |
Large-scale |
Mobile phones, tablets, wearables |
| 03 |
Supplier Profile 03 |
3D forming and curved-display glass |
Chemically strengthened aluminosilicate |
Commercial |
Commercial |
Commercial |
Commercial |
Pilot/Selective |
Medium-to-large |
Curved smartphones, automotive interiors |
| 04 |
Supplier Profile 04 |
OLED display cover and precision CNC processing |
Ultra-clear aluminosilicate, thin chemically strengthened glass |
Commercial |
Commercial |
Selective |
Commercial |
Pilot/Selective |
Medium-to-large |
OLED smartphones, smartwatches, handheld devices |
| 05 |
Supplier Profile 05 |
Thin glass and flexible-display protection |
Thin aluminosilicate, ultra-thin glass |
Commercial |
Selective |
Pilot/Selective |
Commercial |
Commercial |
Pilot-to-medium |
Foldable devices, flexible OLED modules |
| 06 |
Supplier Profile 06 |
Automotive and large-format display glass |
Automotive-grade aluminosilicate, heat-resistant glass |
Commercial |
Commercial |
Selective |
Commercial |
Not listed |
Large-scale |
Vehicle displays, infotainment systems, industrial panels |
| 07 |
Supplier Profile 07 |
Precision small-size cover glass |
Chemically strengthened aluminosilicate, optical glass |
Commercial |
Commercial |
Selective |
Selective |
Not listed |
Medium-scale |
Wearables, mobile devices, cameras, medical equipment |
| 08 |
Supplier Profile 08 |
Decorative and anti-glare display glass |
Aluminosilicate, anti-reflective and anti-fingerprint coated glass |
Commercial |
Commercial |
Selective |
Selective |
Not listed |
Medium-scale |
Consumer electronics, control panels, smart home devices |
| 09 |
Supplier Profile 09 |
High-strength glass with advanced surface treatment |
Chemically strengthened aluminosilicate, low-iron glass |
Commercial |
Commercial |
Commercial |
Selective |
Pilot/Selective |
Medium-to-large |
Premium smartphones, tablets, automotive displays |
| 10 |
Supplier Profile 10 |
Custom glass fabrication and rapid prototyping |
Aluminosilicate, borosilicate, specialty optical glass |
Commercial |
Commercial |
Small-batch |
Small-batch |
Not listed |
Small-to-medium |
Prototype devices, industrial displays, customized projects |
Procurement Analysis: Pricing, Lead Times, Capacity, and Supply-Chain Risk
China Top 10 Full Screen Glass Suppliers in 2026?
Procurement rankings should measure more than production volume. Omdia reported that Chinese manufacturers held about 70% of global TFT-LCD capacity in 2024. However, cover-glass capacity is harder to verify. A practical shortlist should review monthly output, usable yield, coating lines, and backup sites. Standard chemically strengthened glass often costs about US$1.80–4.50 per piece. Complex edge treatments can raise prices by 20% or more. Typical lead times range from three to six weeks. Prototype orders may require eight weeks.
TrendForce’s 2025 display market analysis highlighted continued price pressure across display components. That pressure can hide quality losses. Ask for a twelve-month defect record, not only a quotation. Inspect haze, edge chipping, coating uniformity, and touch-sensor alignment. A supplier with 500,000 pieces of nominal capacity may deliver far less usable glass. This is where many procurement models fail. No ranking remains perfectly stable.
Tips: Request two approved material sources for each critical glass grade. Set a pilot lot before signing annual volume commitments. Keep safety stock near the final assembly site. Verify whether the supplier controls cutting, strengthening, printing, and inspection internally. S&P Global’s supply-chain risk research repeatedly links single-source dependence with longer recovery periods. A low unit price may therefore become expensive during a furnace outage, port delay, or coating-material shortage.